Scott Barnes Kept His IP and Founder Control in a 2026 Beauty Relaunch
The celebrity makeup artist's relaunch shows how founder-led beauty brands can secure outside investment while maintaining IP ownership and putting women in operating control.
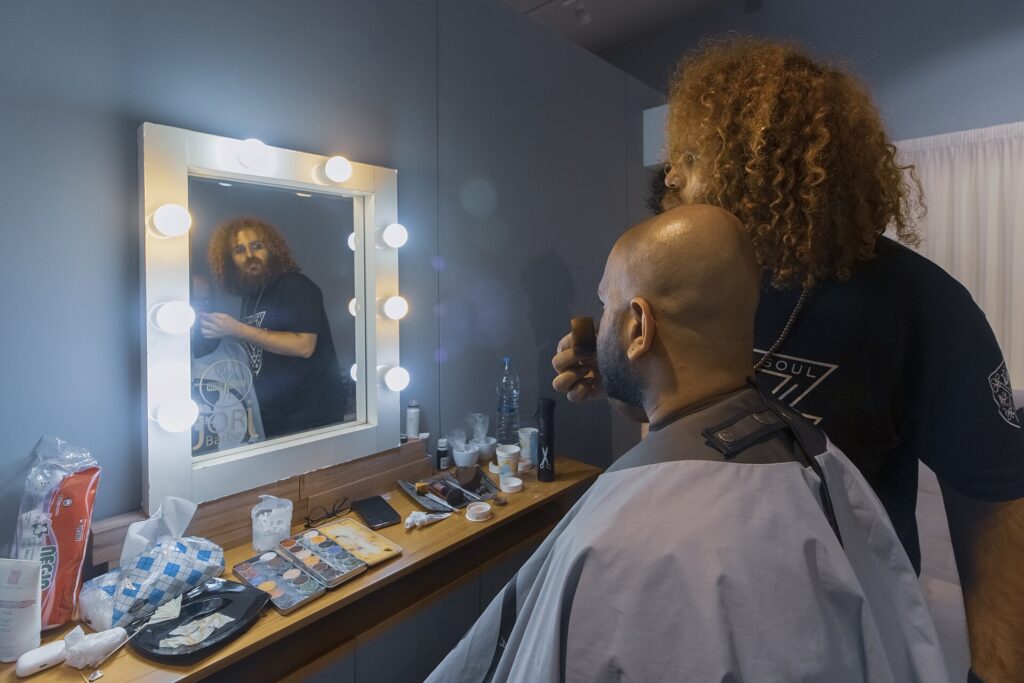
Scott Barnes built his reputation over decades as a celebrity makeup artist before launching his namesake beauty brand on QVC in 2003. His hero product, Body Bling—a sculpting lotion—sold well initially, but operational problems forced the brand to shut down in 2009 despite strong consumer demand.
Seventeen years later, Barnes took a calculated approach to raising capital that reflected a shift in how investors and founders now structure deals. Rather than surrendering control to venture investors or accepting an acquisition that would displace him, Barnes negotiated to keep his intellectual property, required an experienced operating partner, and structured the investment to preserve founder agency. The brand relaunched in June 2026 after securing institutional investment in January. The deal—founder plus institutional capital plus experienced woman operator as equity partner—offers a template that reveals what beauty investors now prioritize: long-term building over quick exits and founder retention over founder replacement.
The relaunch happens as the beauty capital market undergoes structural change. In the first half of 2026, beauty recorded 156 transactions, a 32.2% year-over-year increase after a subdued 2025. But the money is flowing differently than it once did. Investors are scrutinizing businesses for “repeat purchase behavior, strong margins, durable economics, and long-term scalability” rather than simply rewarding revenue growth. That shift in priorities changes what founders must negotiate and what leverage they have.
How investor requirements changed in 2026
The beauty capital market’s recovery in 2026 came with new rules. Investors now want visibility on profitability, clear routes to scale, and credible exit scenarios. They are asking founders harder questions about unit economics, channel performance, and financial discipline.
That scrutiny favors founders who can articulate a business model beyond the product itself. It favors brands with proven consumer retention, measurable repeat purchase rates, and authentic communities around them. Conversely, it punishes founders who chase top-line growth without understanding the economics underneath. For a brand like Scott Barnes Cosmetics—which had consumer demand but no operational infrastructure—this meant investors would fund the business only if the founder brought in someone credible to build systems around the product.
Capital is now flowing toward what investors call “genuine differentiation, credible economics, and the ability to scale.” Funding priorities shifted toward “science-led innovation, supply chain capabilities, wellness adjacencies, and founders capable of building businesses for the next decade rather than the next exit.” That last phrase is critical: investors no longer assume they are buying a path to a quick flip. They are betting on founders to build durable businesses. That assumption gives founders more leverage in negotiating control.
The original brand and its return
Scott Barnes launched his namesake beauty brand on QVC in 2003 with Body Bling, a sculpting body lotion, as the hero product. Operational challenges forced the brand to shut down in 2009 despite strong consumer demand. The 2026 relaunch followed institutional investment secured in January, with the brand focusing on direct-to-consumer and Amazon sales in years one and two.
Narrowing the investor field to protect intellectual property
About 20 prospective investors approached Barnes before he narrowed the field to three finalists. He consulted a biotech mentor and engaged Liza Rapay of Cosmoprof North America to advise the process. The discipline mattered. A mentor advised him that he needed a credible business plan and an operating partner before any capital would move. Those requirements were not obstacles; they aligned with what Barnes wanted anyway.
The investment amount and the names of the specific investors were not disclosed. The capital supported inventory, operating infrastructure, and a focused distribution strategy. But the deal’s structure revealed what mattered most to Barnes: protecting intellectual property. “I wasn’t willing to give away my IP,” he stated in interviews about the relaunch.
That statement is worth unpacking. In traditional venture deals, investors acquire equity in exchange for capital. Founders typically hold a percentage; investors hold the rest. The founder’s formulations, brand name, customer relationships, and creative vision all become part of the assets held by the venture vehicle. When the company exits—through acquisition, IPO, or strategic sale—the investors cash out alongside the founder.
Barnes structured a deal in which his intellectual property remained his own rather than something investors acquired. “When I met these guys—the current investors—they didn’t want to take over my IP,” he said. That arrangement gave Barnes optionality: if the investment didn’t work out as planned, his IP remained his own.
Why an equity partner, not hired management
That operating partner became Crystal Wood, a 30-year beauty industry veteran who joined as Chief Operating Officer and equity partner. Wood previously worked at Estée Lauder Companies, Bobbi Brown, and Tarte. Her appointment signaled that investors expected not just capital deployment, but operational transformation. Wood was not hired as an employee; she received equity, making her a partner with upside participation.
Having Wood receive equity rather than compensation alone changed the incentive structure fundamentally. She had a piece of the upside. Her success was tied directly to the company’s success. Her mandate was to solve the problem that killed the brand the first time: the inability to manage supply chain and fulfillment responsibly. Wood described the original brand’s struggle as a “feast or famine” cycle—periods of fast sell-outs followed by monthslong stockouts, destroying retail relationships and consumer trust.
Wood’s first responsibility was bringing “stability of goods in market.” The relaunch focused on core offerings: Body Bling, professional makeup brushes, and makeup palettes. The strategy was deliberately focused—direct-to-consumer and Amazon for years one and two, with selective returns to QVC only after operations were proven. This phased approach differed sharply from expansion-at-all-costs strategies that had plagued the original brand.
Body Bling now generates roughly 34% of revenue, anchoring the business as it had from the start. By making one product the hero and building around it, rather than chasing every distribution opportunity, the brand created conditions for sustainable growth. The focus also helped Wood manage inventory risk, the exact operational challenge that had sunk the previous iteration.
I wasn’t willing to give away my IP.
Supply chain as strategic capital priority
Over 50% of the brand’s production is US-based, with strategic international sourcing for the remainder. That choice reflects a broader shift in beauty capital allocation. Supply-side investments in beauty surged 87% in the first half of 2026. Institutional investors prioritized manufacturing capabilities, ingredient development, and advanced production technologies that could support the next growth cycle.
The priority signals investor confidence in brands that can control quality and speed to market. A brand relying entirely on overseas manufacturing faces longer lead times, higher minimum order quantities, and supply chain vulnerability. By committing to US-based production for the majority of goods, Scott Barnes Cosmetics reduced the operational risk that had plagued the brand previously.
The brand operates exclusively on full-price selling with no discounts—a discipline that preserves margin and brand positioning. This choice assumes customers are buying solutions for measurable results, not sale events. It also signals to retail partners that the brand will not undermine them through deep discounting, supporting the sustainable wholesale relationships that make long-term retail presence possible.
The commitment to US production also signals something to investors: this brand is not chasing lowest-cost offshore manufacturing or betting on consumer indifference to origin. It is building infrastructure that supports operational resilience. That infrastructure becomes harder to replicate, creating defensible moats around the business.
What founder leverage looks like in 2026 beauty capital
The Scott Barnes Cosmetics structure differs sharply from earlier patterns where institutional investors parachuted in new management or required founders to step aside. It also differs from acquisition, where founders typically lose operational control entirely. Here, the founder retains intellectual property. The operational partner receives equity. The execution role is filled by a woman with deep industry credibility, working alongside Barnes’s creative vision.
This model became possible because investor priorities shifted. Rather than betting on founders to exit quickly and cash out, investors now want founders building businesses for “the next decade.” That long-term view gives founders leverage. A founder can now negotiate terms—IP retention, equity partners instead of hired staff, phased distribution rollouts instead of aggressive expansion—that would have been unthinkable when investors were chasing exits.
Beauty investors increasingly adopt minority-stake investment structures aimed at preserving founder control and the community relationships that drive brand value. This represents a quiet capital revolution in how beauty deals are structured. Instead of the majority-stake approach, where investors control the board and strategic direction, minority stakes preserve founder decision-making while bringing in institutional capital and expertise.
For founders considering outside investment, the Scott Barnes model illustrates what is now negotiable. Protect intellectual property explicitly in deal terms. Require an operating partner who receives equity—someone whose upside is tied to yours. Focus distribution in years one and two to prove operational capability before pursuing aggressive expansion. The founders with the most leverage are those with authentic consumer products, proven repeat purchase rates, and credible founding stories. In that position, you can negotiate from a position of strength.
Photo: Mostafameraji · CC0 · via Wikimedia Commons